The 15-Minute Weekly Money Review: A Simple Routine That Sticks
Most money problems are not disasters. They are small gaps: a direct debit you meant to cancel, a week where the food shop crept up, a savings transfer that never happened because payday felt tight. None of that needs a spreadsheet marathon to fix. It needs noticing.
The fifteen-minute weekly money review is exactly what it sounds like — a short, repeatable appointment with your own finances, once a week, that keeps you close enough to your numbers to make good decisions without turning Sunday into an audit.
Why a weekly review beats a monthly one
Monthly money admin sounds sensible until you try it. By the time you sit down, you are rebuilding four weeks of spending from memory, and the useful details have gone — why the food shop was high, which payment you meant to query, whether that refund ever arrived. You also lose the chance to change anything before another month of the same behaviour has already happened.
A weekly check is short enough that you will actually do it, and close enough to events that you still remember them. Fifteen minutes is roughly one episode of something. In that time you can tidy the week that has just ended, update your log and choose one small thing to do differently.
Set up your kit once
You do not need clever software. You need everything in one place, so the fifteen minutes are not spent hunting for it.
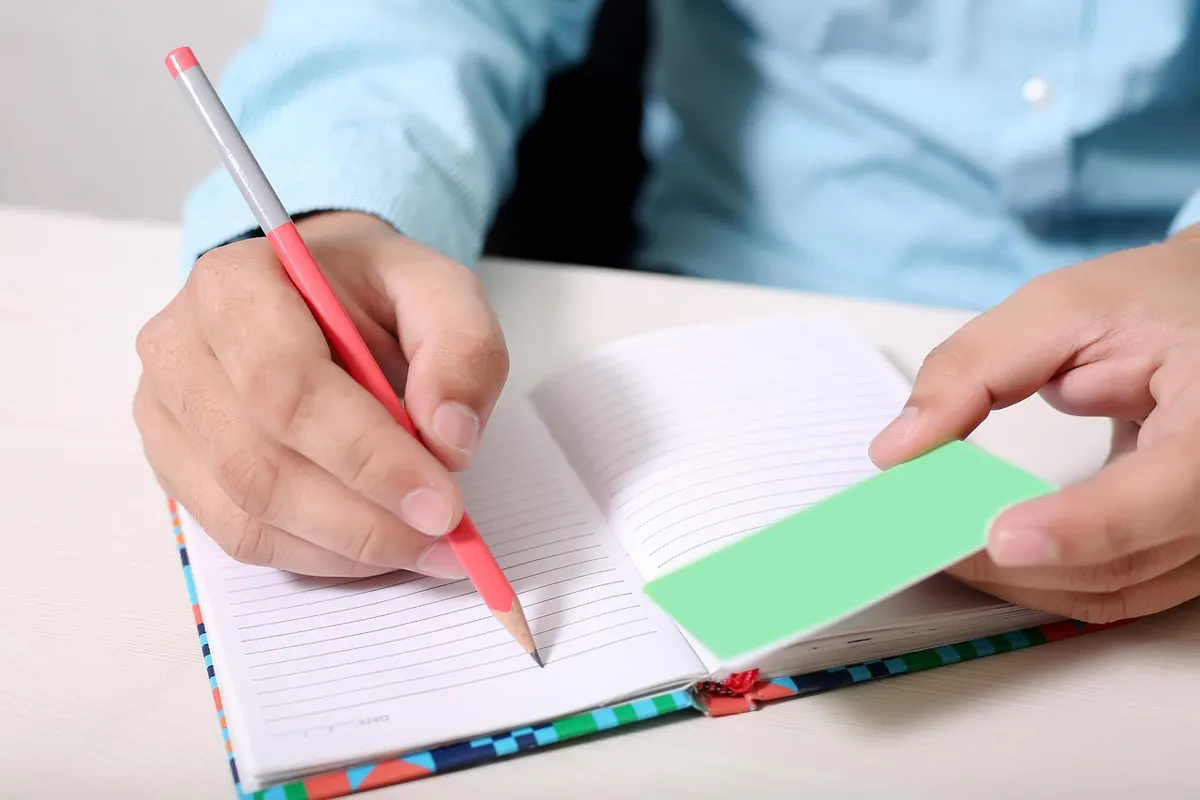
- One log. A notebook, a spreadsheet or an app — pick one and stop moving between them. A single page or tab per week is plenty.
- Access to your accounts. Banking app, credit card, cash. Sign in before you start the timer; two-factor logins eat minutes.
- Your regular payments list. Standing orders, direct debits and subscriptions, with dates, kept somewhere visible.
- A calendar reminder. Same day, same time, repeating weekly. Sunday evening suits a lot of people because the weekend admin is done and Monday is not yet looming.
- A timer. Fifteen minutes, visible. When it goes off, you stop.
The routine, step by step
1. Reconcile the week (about five minutes)
Open your banking app and scroll back to Monday. Take each transaction and match it against your log. You are not auditing; you are spotting.
Mark three kinds of thing: anything you had forgotten, anything larger than expected, and anything that looks wrong — a duplicate charge, a subscription you thought you had cancelled, a fee you do not recognise. If something looks off, note it to query rather than stopping to ring the bank now. Queries can wait until Monday; momentum cannot.
Then check the bottom line. Does the money you actually have match what the log says you have? If not, find the gap before moving on. An unreconciled log quietly stops being useful.
2. Update the log (five minutes)
Write in the week's figures by category, or by whatever broad buckets you use. Groceries, transport, bills, fun and everything else is enough for most households. Add one short line about anything unusual, because next month you will not remember that the car needed two new tyres and the boiler was serviced in the same week.
Those notes turn a list of numbers into something you can read. Over a few months, patterns surface on their own: the weeks that always run over, the categories that creep, the months with two birthdays in them. If you track a savings total, update that too — watching it move is the reward part of the routine.
3. Set one goal for the week (five minutes)
This is the step people skip, and it is the one that changes things. Look at what you have just written and ask one question: what single small money action would make the most difference in the next seven days?
What makes a weekly goal work
Good weekly goals are small, specific and finished by the end of the week. They are about behaviour you control, not outcomes you do not.
- Move a set amount into savings on Wednesday — not "save more".
- Cancel the subscription you noticed again tonight.
- Take lunch from home three days, and decide which three.
- Check the broadband or mobile contract before the renewal date.
- Write a meal plan before the weekly shop, so the shop has a list.
Then name the opposites, the goals that never work: "spend less", "be better with money", "try to save something". They are too vague to succeed or fail, which is exactly why they feel safe and change nothing. Write your one goal where you will see it — in the log, on the fridge, in your phone. One goal, not three.
When the week goes wrong, or you miss a review
Some weeks the numbers are ugly. That is information, not a verdict. Log it, note why, choose the goal, close the book. Shame is a poor budgeting tool: it makes people avoid the log, and avoiding the log is how a small overspend turns into a mystery.
If you miss a Sunday, do not double up the following week. Do a ten-minute catch-up covering both weeks at a broad level, then return to normal. If you miss a month, start again from the current week rather than backfilling. The review exists to inform decisions ahead, not to reconstruct history.
A skipped review is not a broken system. A review you never restart is.
Keeping it going for years, not weeks
Attach the review to something already fixed in your week. After Sunday dinner. Before the bins go out. While the kettle boils. Habits stick when they hang off other habits rather than floating in an empty evening.
Protect the fifteen minutes for the boring parts only: reconcile, log, one goal. Researching savings rates, comparing insurance and rebuilding your whole budget are separate jobs for another day. Letting them in is how a fifteen-minute habit becomes a two-hour one you start avoiding.
Every few months, check the routine itself. Are the categories still right? Have your circumstances changed? Change the log if you need to, not the appointment.
Start this Sunday
Pick a time now, put it in the calendar and set the reminder to repeat. Keep your log and your regular payments list somewhere within reach. When Sunday comes, start the timer and work through three steps: reconcile the week, update the log, choose one goal.
Some weeks it will feel pointless. Some weeks it will catch a duplicate charge or a creeping subscription and pay for itself many times over. The value is in the pattern, not in any single session.
One sensible note: this routine is for everyday household money management. If a review turns up something bigger — problem debt, a tax question, a decision about a pension or an investment — treat that as a signal to get proper advice from a qualified adviser or a free debt charity. Fifteen minutes is long enough to run your week; it is not long enough to solve everything.
Photo: cottonbro studio / Pexels